After a retrenchment or a major financial hit, your bank account can feel like a foreign country. The numbers look wrong. The future feels uncertain. You know you need a system, but the idea of tracking every cent sounds exhausting. You are not alone. Many Singaporeans in their 30s and 40s are looking for a way to rebuild after a crisis. The 50/30/20 budget rule is one of the simplest methods to bring order back into your finances. It is not a magic fix, but it is a clear, structured path that works with the cost of living in Singapore.
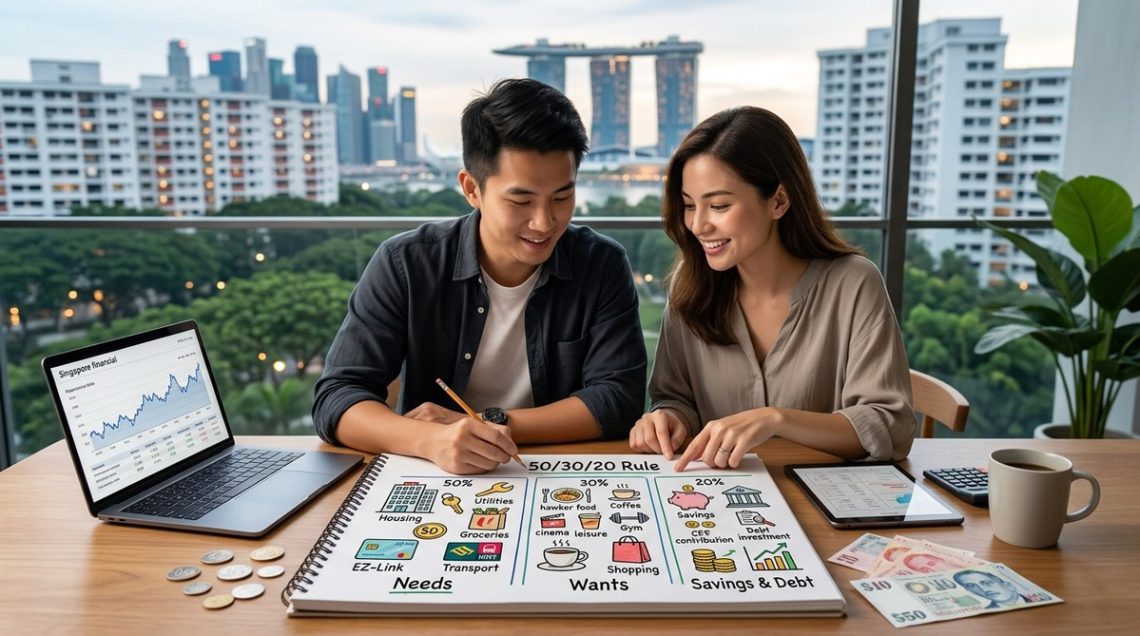
The 50/30/20 budget rule splits your after-tax income into three categories: 50% for needs, 30% for wants, and 20% for savings and debt repayment. For Singaporeans recovering from a crisis, this framework provides a realistic starting point. It helps you cover essentials like rent and utilities, allows some breathing room for small joys, and forces consistent progress on your financial goals.
Why This Rule Fits a Recovery Mindset
When you are rebuilding, complexity is your enemy. You need a system that is easy to remember and even easier to execute. The 50/30/20 rule offers that. It does not require a spreadsheet degree or a finance app obsession. You just need your monthly take-home pay and a rough idea of your spending.
For a Singaporean professional earning a median salary of around S$5,000 per month after CPF contributions, the breakdown looks like this:
- S$2,500 for needs (rent, groceries, transport, insurance)
- S$1,500 for wants (dining out, Grab rides, Netflix, hobbies)
- S$1,000 for savings and debt repayment
This structure is especially powerful after a setback because it forces you to prioritise. You cannot hide from your debt payments. You cannot ignore your savings. The rule acts like training wheels for your financial comeback.
How to Apply the 50/30/20 Rule in Singapore
Let us make this practical. Here is a simple step-by-step process to get started this week.
- Calculate your after-tax income. Add up your salary after CPF deductions and before any voluntary contributions. Include side hustle earnings or freelance income. This is your baseline.
- List your essential needs. These are non-negotiable items. Rent or mortgage for your HDB flat or condo. Utilities like SP Services bills. Groceries from NTUC or Sheng Siong. Public transport fares. Minimum payments on credit cards. Insurance premiums.
- Identify your wants. This is where most people get stuck. Wants include your weekend bubble tea, that new Uniqlo shirt, Netflix subscriptions, and restaurant meals. Be honest. If you can live without it for a month, it is a want.
- Commit the 20% to your future. This portion goes straight to your emergency fund or high-interest savings account. If you have debt, part of this 20% should go towards paying it down faster than the minimum.
“The 50/30/20 rule is not about deprivation. It is about intentionality. When you know where your money is going, you stop feeling like a victim of your circumstances.” – Financial counsellor at a Singapore family service centre
Common Mistakes Singaporeans Make With This Budget
Even a simple rule can go wrong if you are not careful. Here is a table of typical pitfalls and how to avoid them in our local context.
| Mistake | Why It Happens in Singapore | How to Fix It |
|---|---|---|
| Misclassifying needs as wants | Calling your car loan a “need” when a cheaper MRT pass works | Be strict. If you can downgrade your transport cost and survive, the excess is a want. |
| Ignoring irregular expenses | Forgetting annual insurance premiums or road tax | Divide irregular costs by 12 and add them to your monthly needs category. |
| Treating the 20% as optional | Telling yourself “I will save next month” | Automate a transfer to your savings account on payday. Treat it like a bill. |
| Using credit cards to fund wants | Swiping for dinner and calling it a need because you “had to eat” | Cash is psychological. Use a debit card or cash for your wants category. |
Adjusting the Rule for Your Recovery Stage
If you are still in the early phase of your comeback, the standard 50/30/20 split may feel too tight. That is okay. You can modify it temporarily. For example, if you have high-interest debt from a medical emergency or a business loan, you might shift to a 50/20/30 split. This means 50% for needs, 20% for wants, and 30% for debt and savings. The goal is to crush the debt faster.
Once the debt is under control, you can slide back to the standard 20% savings rate. The key is to keep the structure alive. Do not abandon the rule just because your numbers look different.
A Real Example: Rebuilding After a Job Loss
Let us look at a realistic scenario. Mei Ling, 38, was retrenched from her marketing role in early 2026. She had S$8,000 in credit card debt and only S$2,000 in savings. After three months of job hunting, she landed a role paying S$4,200 per month after CPF.
Here is how she applied the 50/30/20 rule:
- Needs (S$2,100): She moved to a cheaper room rental, cut her Singtel plan, and started cooking at home.
- Wants (S$1,260): She limited herself to one coffee shop meal with friends per week and paused her gym membership.
- Savings and Debt (S$840): She put S$500 toward her credit card debt and S$340 into a high-yield savings account.
Within eight months, Mei Ling cleared her credit card balance and built a S$3,000 emergency fund. The structure gave her a sense of control during a chaotic time.
Tools and Resources to Help You Stay on Track
You do not need fancy software, but a few tools can make the process smoother. Consider these options:
- DBS PayLah! or OCBC Pay Anyone for tracking daily spending on wants.
- Seedly or SingSaver for comparing savings accounts with higher interest rates.
- A simple Google Sheet with three columns: Needs, Wants, Savings/Debt.
If you want to strengthen your overall resilience during this recovery, you can read more about how to rebuild your confidence after a major career setback in Singapore. The financial side is only one part of the picture.
When the Rule Does Not Fit Your Life
The 50/30/20 rule is a guideline, not a law. If you live in a household where your parents help with expenses, or if you have a very high rent relative to your income, the percentages will shift. That is fine. Use the rule as a starting point, then adjust.
For example, a young professional living with parents might have needs at only 30% of income. In that case, they can funnel more into savings and debt. The spirit of the rule remains: live within your means, protect your future, and allow yourself some present enjoyment.
Building Momentum With Small Wins
Financial recovery is a marathon. The 50/30/20 rule helps you celebrate small victories. Every time you hit your savings target for the month, you build confidence. Every debt payment brings you closer to freedom.
To keep your motivation high, pair this budget method with a growth mindset. Check out 5 mental resilience techniques every Singaporean professional should master. Your financial habits and your mental strength feed each other.
Your First Step Toward Financial Stability
You have already taken the hardest step. You are looking for a solution. The 50/30/20 budget rule is not a secret formula. It is a proven framework that has helped thousands of Singaporeans regain control after a crisis.
Start today. Open your banking app. Check your last month’s spending. Write down three numbers: your needs, your wants, and your savings target. That is all it takes to begin.
If you need support beyond budgeting, explore the complete guide to debt relief options for struggling Singaporeans. You do not have to navigate this journey alone.
Make This Rule Your Own
The beauty of the 50/30/20 approach is its flexibility. It bends to fit your life, not the other way around. Whether you are paying off debt from a business closure or rebuilding after a medical crisis, this rule gives you a clear lane to drive in.
Start with one month. Track your numbers. Adjust as you go. You will be surprised how much clarity a simple percentage split can bring. Your comeback story is waiting. This budget rule is just the tool to help you write it.